Real-World Asset Tokenization Explained 2026
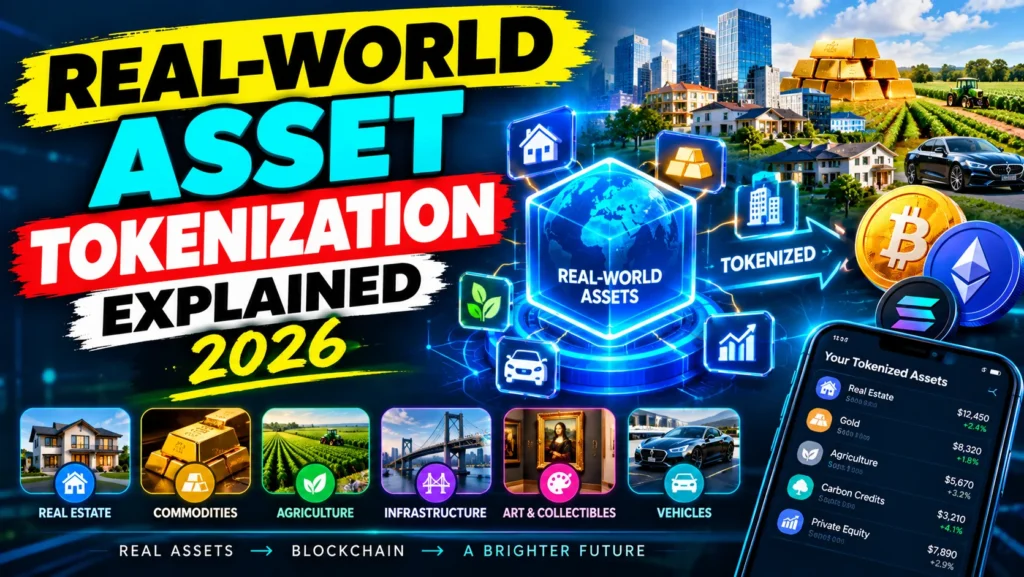
Real-World Asset Tokenization Explained 2026. I’ll be honest, when I first heard “tokenization” I thought it was just another crypto buzzword. It’s not. It’s actually pretty simple.
You take something real like a house, a piece of gold, a US Treasury bond, or even a share of Apple and you make a digital version of it on a blockchain. That digital version is called a token. It’s basically a receipt that says “hey, you own a piece of this.” And you can do a lot with that receipt. Split it into 1000 pieces, sell it at 3 AM, send it to someone in another country in 2 minutes, or lock it up to take a loan against it.
This used to be theory. Now it’s real money. In the first quarter of 2026, the whole market for tokenized real-world assets crossed $50.37 billion. It’s growing at 169% a year. That’s not hype, that’s institutions moving in.
Let me break it down properly.
Real-World Asset Tokenization Explained 2026: Wait, So What Is It Really?
Imagine two completely different worlds.
- On one side you have your dad’s finance world. Full of paperwork, lawyers, banks that close at 5 PM, and settlement takes 2-3 days. Real-World Asset Tokenization Explained 2026. That’s where real estate, bonds, and loans live.
- On the other side you have blockchain. Open 24/7, global, everything settles in minutes, and code handles the boring stuff.
Tokenization is the bridge between them.
And here’s the thing people get wrong tokenizing something doesn’t change what it IS. A house is still a house. Real-World Asset Tokenization Explained 2026. It just changes how that house behaves. Suddenly you can own 0.1% of it. You can trade it like a stock.
How does it actually happen? It’s usually like this:
- First someone picks an asset. Say a rental building.
- Then lawyers set up a special company they call it an SPV whose only job is to legally own that building. Because blockchains can’t own property in court, but companies can.
- Real-World Asset Tokenization Explained 2026, Then a licensed custodian actually holds the deed, or the gold bars, or whatever. They are the grown-up in the room who makes sure the real thing exists.
- Then tokens are minted. Like, 10,000 tokens for one building.
- Real-World Asset Tokenization Explained 2026. And finally those tokens are sold to investors. If you hold 10 tokens, you get 10 tokens worth of rent every month, automatically sent to your wallet. Real-World Asset Tokenization Explained 2026.
- That’s it. Simple idea, powerful execution.
The Tech Under The Hood — Without Getting Too Nerdy
There are 5 pieces working together:
- The blockchain: That’s the ledger. Ethereum is still king for this, but Solana, Polygon, Stellar are all getting a piece.
- Smart contracts: The robots. Instead of an accountant sending rent checks, the code just splits the stable coins and sends them to 500 wallets at once.
- The custodian: The guy with the vault. If this guy is shady, your token is worthless.
- Oracles: The messengers that tell the blockchain “gold is $2,340 today” or “interest rates went up.” Real-World Asset Tokenization Explained 2026.
- Compliance: The ID check. It makes sure only approved people can buy and sell certain tokens.
So What’s Actually Been Tokenized? The Numbers in 2026 Are Wild
This market is no longer just about stablecoins.
Credit and Private Loans: $25.65 Billion
Real-World Asset Tokenization Explained 2026., This is the giant. By far the biggest category. It’s mortgages, corporate loans, things that used to be buried in bank databases. A company called Figure is literally putting home loans on-chain. The whole loan documents, payments, everything.
Treasuries and Money Market Funds: $14.26 Billion
- This is where Wall Street woke up. BlackRock launched BUIDL back in March 2024 and by late 2026 it was at $2.8 billion. It lives on 8 different chains now.
- Institutions love it because it does what a normal money market fund can’t. It pays yield daily, trades on weekends, and you can use it as collateral while it’s still earning yield.
Commodities, Mostly Gold: $7.30 Billion
88% of this is just gold tokens. Tether Gold alone is $2.52 billion. Why? You can buy $50 of gold, not a whole bar. And you can trade it at midnight.
Other Stuff — Real Estate, VC, Art: $2.19 Billion
Still small, but Deloitte is saying tokenized real estate funds could hit $1 TRILLION by 2035. That’s insane.
3 Real Examples So You Actually Get It
1. The $100 Real Estate Investor
You want to invest in a fancy apartment building but you don’t have $2 million. Platforms like RealT buy the building, put it in an LLC, tokenize the LLC. You buy one token for $100. You get $0.50 in rent every month in USDC. You can sell that token next week if you want. You’re a landlord without the headaches.
2. The Hedge Fund Using Tokens as Collateral
Franklin Templeton’s token is called BENJI. The SEC actually said, okay, other mutual funds can hold BENJI directly. So a fund can hold $10M in Treasuries, earn yield, and at the same time pledge that same $10M as collateral to make another trade. Before, you had to choose one or the other.
3. The Guy Outside The US Buying US Stocks
Ondo is doing this. They hold real Apple stock or a real ETF in a brokerage account, then issue tokens that track it on Ethereum, Solana, BNB Chain. So someone in Pakistan or Nigeria who can’t open a Robinhood account can still get exposure to US stocks and trade 24/7.
Why People Are Excited — The Real Benefits
- Fractional ownership. You can finally own a sliver of things that were only for millionaires.
- Liquidity. Try selling a house in 10 minutes. You can’t. But you can sell a house token in 10 minutes.
- It’s programmable. Rules like “only sell to investors who passed KYC” or “pay dividend on the 1st of every month” are baked into the code. No middleman.
- Fast settlement. Traditional settlement is T+2. Two days. On-chain is T+2 minutes.
- Transparency. Every move is on a public record. Harder to fake ownership.
Now For The Part No Influencer Tells You — The Risks
I have to be blunt here because people lose money ignoring this.
- A token is not legal ownership by itself. I’ll say it again. The blockchain record means nothing if the legal paperwork behind it is garbage. If the SPV that holds the building collapses, your token is a useless souvenir.
- Regulation is a total patchwork. A token that’s totally legal in Singapore might be considered an illegal security in the US. The EU has MiCA which is pretty clear, the US is still figuring it out. You need to know YOUR country’s rules.
- There’s no one to sell to. This is the biggest problem right now. Pantera Capital said it perfectly “Issuing is easy, liquidity is hard.” Anyone can create a token. Finding a buyer when you want to sell? That’s the hard part. Lots of these markets are dead quiet.
- Custodian risk is real. You are trusting one company to actually hold the asset. If they go bankrupt like FTX did, or they lie about the gold, you’re screwed. And there’s no FDIC or SIPC insurance for most of this.
- Tech risk. Smart contracts have bugs. People lose seed phrases. If you send tokens to the wrong wallet address, there’s no customer service to call. It’s gone.
Also Check: Dropshipping, Print on Demand & Affiliate Marketing for Beginners 2026 Guide
Mistakes To Avoid
- Mistake #1: “It’s on the blockchain so I legally own it.”
Nope. Always ask: Who is the legal owner? Show me the SPV docs. Who is the regulated custodian? - Mistake #2: “If I can buy it, it must be legal for me.”
No. Many tokens are geo-blocked. If you buy something you’re not supposed to, you could get stuck holding something you can’t legally sell. - Mistake #3: “No taxes because it’s crypto.”
Wrong. If you earn rent or interest from a token, you owe tax. Tokenization doesn’t hide you from the taxman. - Mistake #4: “The token price IS the asset price.”
Not always. In illiquid markets, a token for a $1M house might trade at $1.3M or $700k. Always check the underlying Net Asset Value.
How I Personally Evaluate Any Tokenized Project?
Before I even think about it, I ask 7 questions:
- What’s the legal wrapper? Is it a real trust/SPV?
- Who is the custodian? Have I ever heard of them? Are they regulated?
- What rights does the token actually give me? Income? Can I redeem it for the real thing?
- Can I sell it freely or am I locked for 12 months?
- Which chain is it on? Is my wallet even compatible?
- How do they handle KYC/AML?
- What are the hidden fees? Minting, 2% management, redemption fees it all eats your profit.
Where Is This Heading?
- This isn’t going to replace banks. That’s a fantasy.
- What’s actually happening is that J.P. Morgan, HSBC, Fidelity they are all building on this tech. In 2026 they all launched tokenized products. Robinhood did $887.5 million in a single week just trading tokenized stocks.
- The future is two rails running side by side. The old traditional rail, and the new blockchain rail. And slowly, more stuff is moving to the faster rail.
- For regular people like us, the opportunity isn’t to chase the next 100x token. It’s to understand how ownership itself is changing.
Frequently Asked Questions
In one line, what is RWA tokenization?
Making a digital token on a blockchain that represents ownership of a real thing like a house, gold, or bond.
Can anyone buy these?
No. A lot of them are still only for accredited investors or rich individuals, especially in the US.
How is it different from stable coins?
Stablecoins = digital dollars. RWA tokens = digital houses, bonds, gold, stocks.
Do they pay yield?
Some do, some don’t. Money market tokens pay daily. Real estate tokens pay rent. Gold tokens don’t gold doesn’t pay yield anyway.
Can I use them as collateral?
Yes, and that’s why institutions love them. BUIDL is already used as collateral everywhere.
Will this kill traditional finance?
No. It’ll make it faster. Think upgrade, not replacement.
Conclusion
Tokenization is a tool. A really powerful tool. It makes ownership more accessible and markets more efficient.
But a tool doesn’t make a bad investment good. A crappy apartment building is still a crappy investment even if you tokenize it into 10,000 pieces.
Value comes from the asset, not the technology wrapping it. Never forget that.
So what do you think if you could tokenize any asset class tomorrow, what would you pick? Real estate? Private credit? Something else? Drop your thoughts below.
One Comment