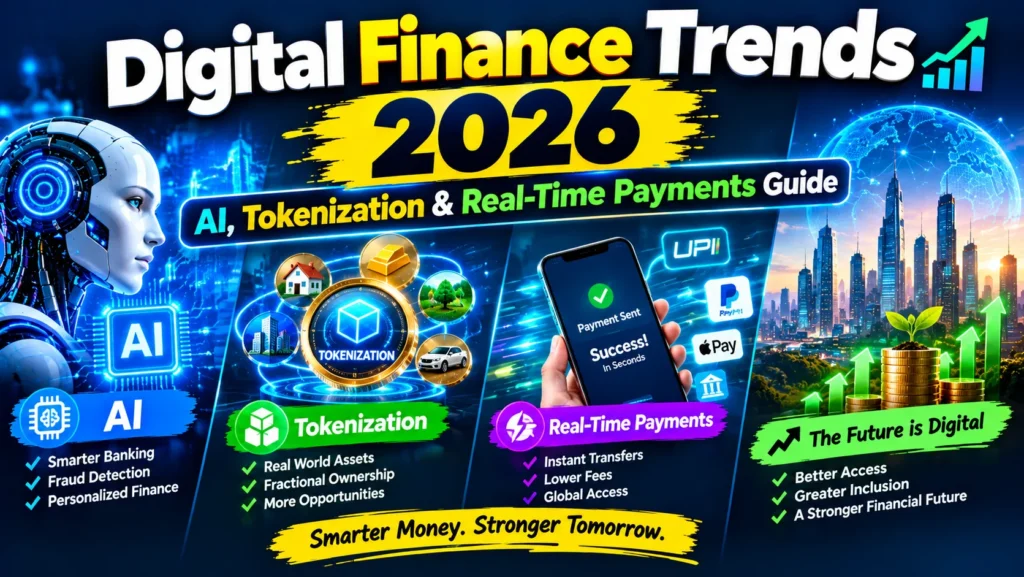
Digital Finance Trends 2026: AI, Tokenization & Real-Time Payments Guide
Digital Finance Trends 2026. Listen, money doesn’t feel like money anymore. Seriously. Back in 2021-22, if someone said “digital finance” I thought of JazzCash and my HBL app crashing every time I needed it. That was it. That was our big digital finance.
Yesterday? I paid for my In Driver ride without opening my bank app. My client in Dubai sent $300, I just sent him a QR and it landed in like 60 seconds. No Wise drama, no “2-3 business days”. And my friend Asif who has that mobile shop near Hussain Agahi in Multan he messaged me “yar Daraz is offering me loan inside seller panel”. He didn’t go to the bank. The bank is now INSIDE Daraz.
This is not some future prediction for 2030. It’s already in your pocket. If you’re freelancing, if you have a small shop, even if you’re just trying to save 20-30k a month, this stuff is changing everything for you. I deal with this daily so let me break down what actually matters in 2026. No textbook definitions, I promise.
Digital Finance Trends 2026: Why 2026 is Actually Different
We heard the same BS for 5 years. “Blockchain will change finance.” “AI will change banking.” We all got bored because nothing changed for us normal people.
This year it’s different for 3 real reasons.
- Government finally stopped playing. US, UK, UAE, EU, Singapore – they made actual proper rules. Not ban today, allow tomorrow. When rules are clear, big companies actually build.
- Big guys stopped doing fake pilots. JPMorgan, Visa, Nasdaq – they are not making LinkedIn posts anymore. They put this stuff inside their real systems. The ones that move actual billions.
- We lost patience. If payment is not instant now, we uninstall. Nobody waits for “your funds will settle in 48 hours”. No one.
So yeah, the pipes under the ground the ones that move money they actually changed this time.
1. Tokenization – Finally Not Just PowerPoint
- I was so sick of hearing this word. Tokenization. Every conference, same slide for 6 years. But last few months I saw it live.
- Think like this you have a real asset. House, shop, bond, gold. You make a digital receipt of it on blockchain. That receipt is a token. Now you can cut that one receipt into 100 pieces and sell it in 10 minutes. No patwari, no stamp paper for 3 months.
- Why I’m believing it now? ECB said in Feb this year tokenized stuff on public chains crossed $45 billion. In early 2024 it was like $8.4b. It’s still tiny for whole finance world but growth is insane. IMF also said in their 2026 report – it’s not demo anymore.
For us normal people what does it mean?
You don’t need 2 crore to invest in a plaza. You can buy a $50 token of it. And when you sell, you don’t wait T+2 days for money. It’s almost instant. I have a cousin with land in Vehari, stuck for 2 years, no buyer. If that land was tokenized he could have sold half of it in parts by now.
One thing though – my filter is simple. If the project can’t answer “who is ACTUALLY holding the real property on paper?” I don’t touch it. Speed is good but crash is also fast. IMF warned about that too.
2. Stable coins Won. Not Bitcoin.
If there is one clear winner in 2026, it’s stablecoins. Not even close.
Two years back, like 92% of stablecoin use was just crypto traders moving money from Binance to Bybit. Only for trading. Now? Totally different. Western Union made its own dollar stablecoin so it can settle even on Sunday night. Tether launched a wallet that works in 160 countries and my mama can use it without knowing what gas fee means. It just works.
What I see daily:
- My team guy in Multan – his brother sends from Saudi. Old way – $18-20 fee, 2 days. Stablecoin way like $0.20, 2 minutes. I literally saw the screenshot.
- Second, when dollar goes up, people in Pakistan just keep USDT on phone. It’s like having a dollar account without needing a US bank.
- Third, you can get a Visa card now that spends straight from your USDT. Tap everywhere.
- But please don’t think stablecoin = safe like bank cash. It’s NOT safe like that. If the company messed up its reserves, or everyone panics at once, it can go to zero in one night. IMF said clearly it can hurt the whole system.
- I use stablecoins to MOVE money. Not to keep my life savings. If I keep big amount, I always check who is the issuer and how I can redeem it back to real dollars.
Also Check: Non-Custodial Wallets Explained 2026: Complete Self-Custody Guide
3. Real-Time Payments Are Normal Now
- Instant used to be a premium feature. Now if your app doesn’t have instant, you look like you’re from 2015.
- As of June 2026, 137 countries have instant payments 24/7. World Bank talked about why.
- Cash doesn’t get stuck. When a small shop gets paid instantly, he pays his supplier instantly. For small business, cashflow is everything. It’s jaan.
- And every instant payment leaves a trail. So even if a shop has no credit history, lender can see “ok this shop does 50k sale daily” and give loan.
- Numbers are crazy – Thailand’s PromptPay can add 2% to GDP. Brazil’s Pix will add like $49.9 billion to formal GDP by 2028.
- If you have any business – please. This week call your payment gateway and ask “do you support Raast, UPI, Pix, FedNow, SEPA Instant?” If they say no, change them. And put that instant option right on your checkout page next to cards. Customers WILL pick it.
4. AI Is Not Chatting Anymore, It’s Doing The Work
- We all played with ChatGPT. 2026 is different. Now we have AI agents that actually DO the kaam, not just talk about it.
- Nasdaq put agentic AI inside their Calypso platform. Agents handle full trade – matching, risk checks, talking to other agents – without human clicking every button. With compliance locks obviously.
- Broadridge said their agents are live – they handle failed trades, account opening, valuation mistakes. They claim 30% cost cut.
- Even if you’re not a trader, you feel it:
- Your card gets used at 3am in another country – blocked in 1 second by AI. You are a Careem driver or freelancer with no salary slip old bank says no loan. Now AI looks at your real income pattern and can give small loan. That support that made you wait 30 mins now fixes small issues in 10 seconds.
- But Bank of Thailand said something scary and true – when agents become so powerful, we stop checking them. We just trust blindly. One wrong auto-decision and huge loss.
- My rule – never ever give AI full control of your money without a review button and undo button. Never.
5. Banking Became Invisible
- Funny thing we use banking more than ever, but we open bank apps less than ever.
- Last week id you pay for ride inside ride app? Did you choose “Pay in 4” at checkout? Got insurance offer while booking flight? Got loan offer inside Amazon seller panel?
- That’s embedded finance. Finance hiding inside normal apps.
- World Economic Forum says this will be $7.2 trillion by 2030. Banks are not dead. They are just working in the background. That’s why people call it invisible banking.
- If you have app or website or store – you can offer finance without becoming a bank. Just use Banking-as-a-Service API.
- What I have seen work – Offer BNPL on checkout, sales jump 20-30% straight. Offer working capital to your own sellers, they never leave you.
- Tech is easy, law is hard. You still have to do KYC, AML, privacy. Just because your BaaS partner does tech doesn’t mean you are free from law.
6. Open Banking Is Now Open Finance
- Started as – let an app see your bank data if you allow. Now it’s bigger. Open finance.
- Not just bank accounts. Investments, insurance, pension, loans – full picture.
- India is leading crazy – Account Aggregator crossed 325 million linked accounts by July 2026. UK Open Banking APIs are at 99% success rate now, super stable.
What you get?
- Better loan offers. Lender sees your full discipline, not just salary slip. So even without big credit score you can get lower rate if you are responsible. One app shows all your banks and investments. No need for 6 apps.
- Risk though is real. OECD 2026 report said biggest risk now is scams. 69% countries said scams increased from 2024 to 2025. More data sharing = more phishing.
- What I do – every 2 months I open my banking app, go to connected apps, and remove access for anything I don’t use. Takes 2 minutes. You should do same.
7. CBDCs – Government’s Own Digital Cash
Digital Finance Trends 2026. CBDC means Central Bank Digital Currency. Digital cash from your central bank. Not from Tether.
115 central banks are exploring retail CBDCs, 4 have fully launched, 12 are in pilot with real users. ECB finished prep for digital euro in Oct 2025. Good side you hold central bank money directly, government payments like BISP or subsidies can come instantly.
Worries – privacy. Digital Finance Trends 2026. Will central bank see all your spending? Depends how they design it. And adoption is hard. Peru pilot struggled because CBDC didn’t work well with normal bank accounts. Digital Finance Trends 2026. Nigeria’s eNaira is used by less than 1% people. And if everyone moves money to CBDC, banks will have less money to give as loans.
For most of us CBDC won’t replace cash tomorrow. Digital Finance Trends 2026. But if your country is testing it, keep an eye.
Mistakes I See Every Week
- Chasing 20% yield without asking where yield is coming from. If someone offers 20% on staking and starts mumbling when you ask where it comes from, run.
- Ignoring how good scams became. Digital Finance Trends 2026. AI made scams perfect. Voice cloning, deepfake video calls. Digital Finance Trends 2026, If someone asks for money, always verify with a separate call. Always.
- Thinking regulation protects you everywhere. What is legal in UAE might be banned in US. Check your local law.
- Only offering one payment method. Digital Finance Trends 2026. Don’t just take cards. Offer 3-4 options, especially instant.
- Clicking Accept without reading. Every time you connect bank, you share data. Read that consent screen.
So What To Do Now?
Digital Finance Trends 2026. You don’t need to learn everything.
For you personally:
Turn on instant receive – Raast, UPI, Pix, whatever your country has. If you hold crypto or stablecoins, know where your private keys are. Exchange or self-custody? How do you cash out at 2am in emergency? And check which apps have access to your financial data.
If it sounds too good to be true, it IS too good.
For business:
This week ask your processor about instant rails. If they don’t support, find one who does. Can you offer installments at checkout? Can you pay your merchants faster? That builds loyalty like crazy. And with instant payments, fraud is also instant. You need AI fraud detection now, not later.
Frequently Asked Questions
Biggest trends in 2026?
Tokenization finally real, stablecoins used for daily payments, instant payments in 137 countries, AI agents doing finance work, banking hiding inside apps, open banking becoming open finance, and CBDC pilots.
Is tokenization safe?
Upside is real – fractional ownership, instant settlement – but some products have zero legal papers. Start small, check documents.
Will AI replace advisors?
No. AI is good for data, but for life decisions you still need human.
What is embedded finance?
Finance inside non-finance apps. You pay inside Uber, you get loan inside Shopify.
How to protect from fraud?
2FA on everything, don’t trust urgent money requests, verify via separate call, be careful with voice notes and video calls – they can be faked now.